Credit Repair Before Buying a House: 2027 Guide
Buying a home is a major financial milestone. But inaccurate late payments, collection accounts, charge-offs, and other credit reporting problems can complicate mortgage underwriting—or potentially affect the financing terms available to you.
You do not need perfect credit to buy a house. What matters is understanding what lenders review, identifying genuine reporting errors, and making informed decisions before applying. This guide explains what to check, what you can dispute, how long corrections may take, and how to avoid costly mistakes.
Quick Answer: Should You Repair Your Credit Before Buying a House?
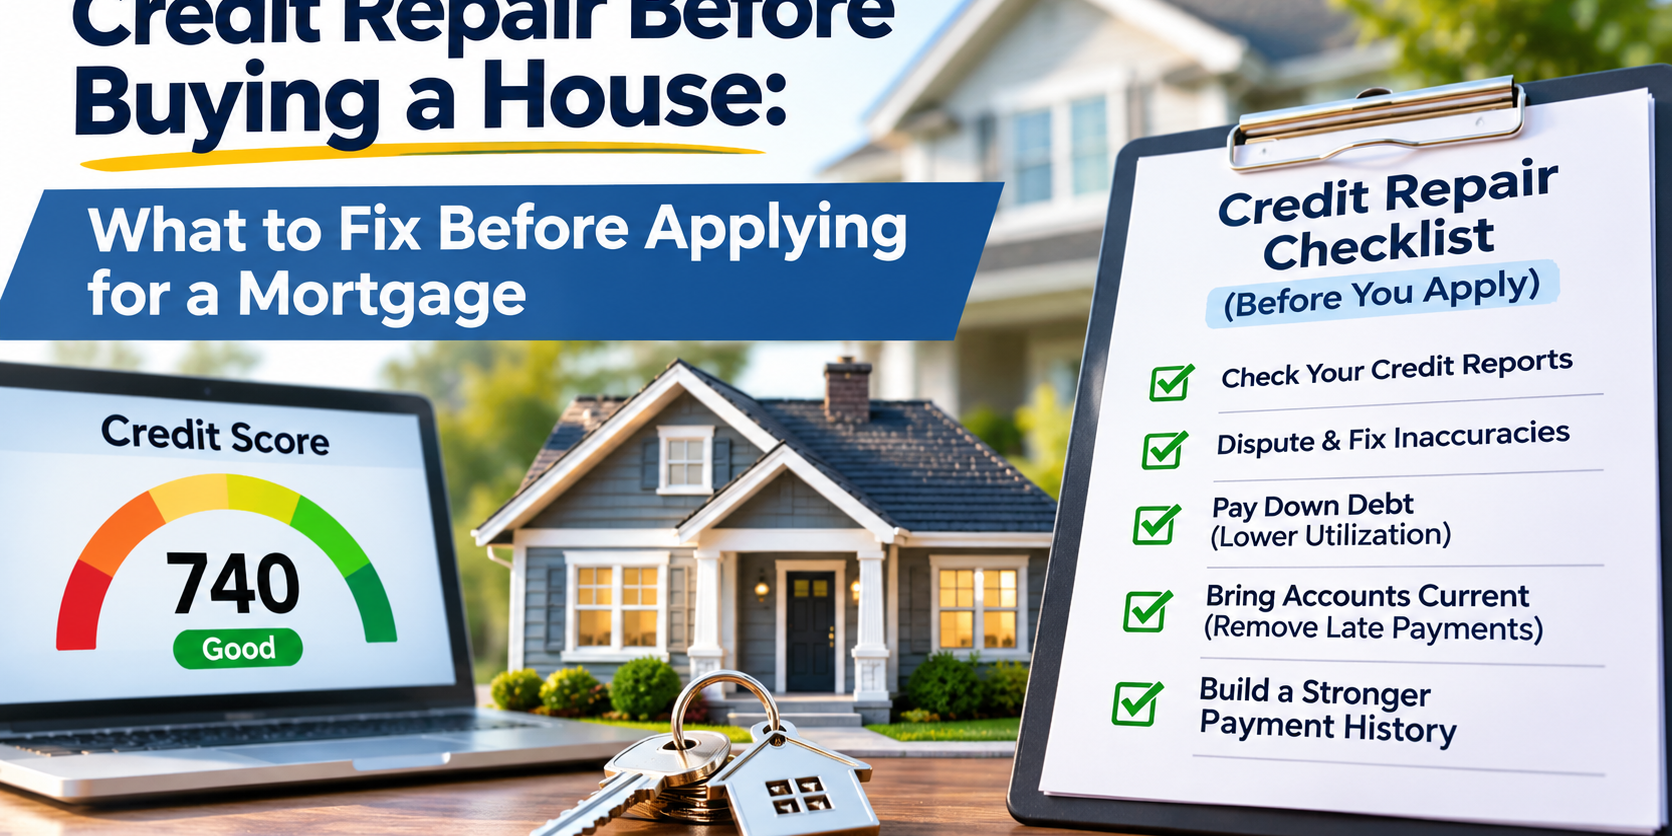
Reviewing your credit reports and correcting inaccurate information before applying for a mortgage can help you avoid underwriting complications. Ideally, start three to six months before applying. Check all three reports for incorrect collections, late payments, balances, and account statuses. Paying down high credit card balances may also help your scores. Credit repair cannot guarantee a score increase or mortgage approval.
Key Takeaways
- Start early: Review your reports three to six months before applying, or earlier if you expect complicated issues.
- Check all three bureaus: Experian, Equifax, and TransUnion may report different information.
- Dispute actual errors: Inaccurate late payments, collections, balances, and account statuses deserve investigation.
- Manage utilization: Lower revolving balances may improve scores after updated balances report.
- Talk to your loan officer: Collections and active dispute notations can affect underwriting differently across programs.
- Know the limits: Accurate, timely negative information generally cannot be removed simply because it hurts your score.
Why Credit Matters When Buying a House
Mortgage lenders assess your credit reports, credit scores, income, debts, assets, and other financial information. Credit can affect both eligibility and the interest rate or terms you are offered. Different lenders and loan programs have different requirements; there is no single minimum score that applies to every mortgage.
How Much Can a Different Mortgage Rate Cost?
Consider a hypothetical $300,000, 30-year fixed-rate mortgage:
| Interest rate | Monthly principal & interest | Approximate total interest |
|---|---|---|
| 6.0% | $1,799 | $347,515 |
| 6.5% | $1,896 | $382,633 |
| 7.0% | $1,996 | $418,527 |
| 7.5% | $2,098 | $455,152 |
Illustrative rates and rounded calculations—not current mortgage quotes. Figures exclude property taxes, insurance, mortgage insurance, fees, and other costs. A better credit score does not guarantee a specific rate.
At 7% rather than 6%, the monthly principal-and-interest payment is approximately $197 higher. This illustrates why understanding your credit before shopping for a mortgage matters.
What Credit Problems Should You Review First?
1. Inaccurate Collection Accounts
Collections may affect credit scores and trigger underwriting questions, but they do not automatically disqualify you from obtaining a mortgage. Treatment depends on the loan program, the type of collection, balances, and lender requirements. Check the ownership, balance, dates, and account status. If the information is inaccurate, incomplete, or unverifiable, you may have grounds to dispute it. Paying a collection does not automatically remove it from your credit reports.
2. Incorrect Late Payments
Recent 30-, 60-, and 90-day delinquencies can be significant to lenders. Compare reported payment histories with statements and payment confirmations. Examples of possible errors include payments reported late despite timely receipt, incorrect dates, or a payment applied to the wrong billing period. Under the Fair Credit Reporting Act (FCRA), consumers can dispute inaccurate or incomplete reporting.
3. Charged-Off Accounts
A charge-off is an accounting classification; it does not necessarily cancel the debt. Review outstanding balances, dates of first delinquency, payment history, and whether an account was sold or transferred. The federal credit-reporting period is different from a state’s statute of limitations for filing a collection lawsuit. Read more about debt statutes of limitations.
4. High Credit Card Balances
Credit utilization compares revolving balances with available credit. A $4,500 balance on a $5,000 limit is 90% utilization; reducing it to $1,000 would bring utilization to 20%. Lower utilization often benefits scores, although no percentage guarantees a particular result. Updates generally become visible after the creditor reports the new balance.
5. Accounts That Are Not Yours
Mixed credit files, identity theft, and data-entry errors can place another person’s information on your report. Review account ownership and identifying details, and dispute records that do not belong to you.
What Should You Fix First Before Applying for a Mortgage?
| Issue | First step | Why it matters |
|---|---|---|
| Inaccurate collection | Document and dispute the specific error | Can affect scores and underwriting |
| Incorrect late payment | Compare statements; request correction | Payment history can weigh heavily |
| High card balances | Consider paying down revolving debt | May reduce utilization |
| Charged-off account | Verify balance, dates, and ownership | Can affect credit and lender review |
| Wrong personal details | Request correction | Can help prevent file-matching errors |
| New financing | Avoid unnecessary applications | May affect debt-to-income and credit |
Important distinction: Inaccurate reporting calls for an accuracy-based dispute. Accurate debts and valid negative history generally require different decisions, such as repayment planning or discussions with your mortgage professional.
How Long Does Credit Repair Take Before Buying a House?
There is no guaranteed timetable. Credit reporting agencies generally have 30 days to investigate disputes, with extensions possible in certain circumstances. A correction can also take additional time to appear in a lender’s reports or scores.
| Time before applying | Suggested focus |
|---|---|
| 30 days | Identify urgent errors, review balances, coordinate with your loan officer |
| 60 days | Review initial dispute outcomes and updated balances |
| 90 days | Allow more time for investigations, corrections, and follow-up |
| 6+ months | Build a broader plan for payment history, debt reduction, and reporting accuracy |
Starting early provides flexibility, but a 30-, 60-, or 90-day window is not a promise that an account will be corrected or that a score will improve.
Should You Dispute Collections While Applying for a Mortgage?
You retain the right to dispute inaccurate information, but active disputes can complicate underwriting for some loan programs. A lender may request documentation, review a dispute notation, or require certain issues to be resolved. If you are already applying or under contract, discuss the timing with your loan officer. Removing a dispute notation is not the same as correcting the underlying account.
Can You Buy a House With Collections?
Yes, some borrowers qualify for mortgages with collections on their credit reports. The answer depends on the loan program, account type, balance, overall credit profile, and lender-specific underwriting rules. Some unpaid collections may be allowed; others may need additional consideration. Before paying a collection solely for mortgage approval, ask your lender whether it is required and how payment would affect your closing funds.
Should You Pay a Collection or Dispute It First?
First determine whether the account is yours and whether the information is accurate. Dispute genuine reporting errors. If the debt is valid, weigh repayment or settlement against your lender’s requirements and overall finances. In some states, acknowledging or paying an old debt can affect the statute of limitations for a collection lawsuit. Consider legal advice if that issue is relevant.
How to Dispute Credit Report Errors Before Buying a House
- Get all three reports. Visit AnnualCreditReport.com, the federally authorized source for free credit reports.
- Identify specific inaccuracies. Record the bureau, account, reported field, and reason the information is wrong.
- Collect supporting records. Payment confirmations, statements, settlement letters, or correspondence can help support your position.
- Submit an accurate, specific dispute. The FCRA generally requires credit reporting agencies to conduct reasonable reinvestigations. Certain disputes may also be submitted directly to furnishers.
- Review the results. If the information remains inaccurate, consider appropriate follow-up, additional evidence, or a regulatory complaint.
Learn about your rights under the FCRA and the Fair Debt Collection Practices Act (FDCPA).
Seven Mistakes to Avoid Before Mortgage Closing
- Opening new credit accounts without discussing the impact with your lender.
- Financing a car or other large purchase that increases monthly debt obligations.
- Closing older credit cards and unexpectedly raising utilization.
- Missing payments while waiting for mortgage approval.
- Paying collections without understanding lender requirements or cash needs.
- Assuming a consumer-app credit score is the score your mortgage lender will use.
- Waiting until underwriting begins to review your reports.
Why Your Credit Karma Score May Differ From Your Mortgage Score
Credit-monitoring services and mortgage lenders may use different scoring models and bureau data. Credit Karma commonly displays VantageScore scores, while mortgage lenders may use specific FICO models or other models permitted under applicable program requirements. A difference between scores does not necessarily mean one is wrong. Ask your loan officer which reports and scores will be used.
A Practical Credit-Report Review: Look for the Specific Error
For a productive credit-report review, avoid treating every negative entry as an error. For example, a collection account may have a legitimate balance but an incorrect date, or a credit card may be accurately reported as charged off while showing an outdated balance. The most useful starting point is to identify the exact field in question, compare it with available documentation, and determine what correction is warranted.
This accuracy-first approach helps consumers distinguish issues suitable for an FCRA dispute from matters better addressed through repayment planning or lender guidance.
How CreditFirm.net Can Help
CreditFirm.net has assisted consumers with credit reporting issues since 1997. We help identify and challenge potentially inaccurate, incomplete, unverifiable, or otherwise noncompliant information reported by Experian, Equifax, and TransUnion. Common issues include collection accounts, charge-offs, late-payment histories, balances, account statuses, and certain inquiries.
Consumers can dispute credit report errors themselves for free. Our service is intended for people who prefer professional assistance with the review and dispute process. We cannot guarantee account deletions, score increases, particular loan terms, or mortgage approval.
Pricing: $49.99 per month, pay as you go, with the ability to cancel anytime.
Frequently Asked Questions
How early should I start reviewing my credit before buying a house?
Ideally, three to six months before applying, or earlier if you anticipate complex reporting issues. Starting early allows time to review reports, submit disputes, and evaluate the results.
Can credit repair help me qualify for a mortgage?
Correcting inaccurate information may improve your credit profile, but qualification also depends on income, debts, assets, loan requirements, and other factors. No credit repair company can guarantee mortgage approval.
Can I buy a house with a 600 credit score?
Possibly. Some mortgage programs and lenders accommodate borrowers around that score, depending on the full application. Ask a qualified mortgage professional about current eligibility requirements.
Do I have to pay collections before buying a house?
Not always. Requirements vary by mortgage program, collection type, and lender. Consult your loan officer before paying solely to satisfy underwriting.
Will paying a collection raise my mortgage score?
Not necessarily. The effect depends on the scoring model and your credit file. Paying a collection does not automatically delete it from a report.
Can I dispute late payments during mortgage underwriting?
Yes, if the reporting is inaccurate. However, active dispute notations may prompt additional underwriting review, so coordinate timing with your lender.
Is paying down credit cards better than disputing collections?
They address different issues. Reducing revolving balances may improve utilization after updates report. Inaccurate collections should be challenged on their merits, but dispute outcomes and timelines are not guaranteed.
Does checking my own credit hurt my score?
No. Checking your own credit is a soft inquiry and does not reduce your credit scores.
Final Thoughts: Start Before You Shop for a Home
Mortgage preparation is easier when you understand your credit reports before a lender reviews them. Identify inaccurate information, reduce avoidable credit risks, and coordinate decisions with your loan officer. The goal is an accurate credit history—not an artificially perfect one.
About This Article
Reviewed by CreditFirm.net. CreditFirm.net has provided consumer credit repair services since 1997, focusing on credit reporting disputes and consumer rights under federal law.
Last reviewed: November 2026.
References and Further Reading
- CFPB: Prepare your finances to buy a home
- CFPB: How to dispute a credit report error
- CFPB: Credit scores and mortgage rates
- AnnualCreditReport.com
- Fannie Mae Selling Guide
General consumer education only, not individualized mortgage, financial, or legal advice. Mortgage requirements change and vary by lender and program. CreditFirm.net cannot guarantee a particular credit score, deletion, or mortgage approval.
Why Choose CreditFirm.net?
Assurance. Our Credit Repair process was developed by experienced attorneys.
Speed. Documents are typically processed and sent out for investigation within 3-5 days.
Support. Award-winning customer service guarantees your satisfaction.